Profile
About
My research is on measuring and forecasting risk in financial markets: tail risk (Value at Risk and Expected Shortfall), information entropy, speculative bubbles and crashes, digital assets and energy markets.
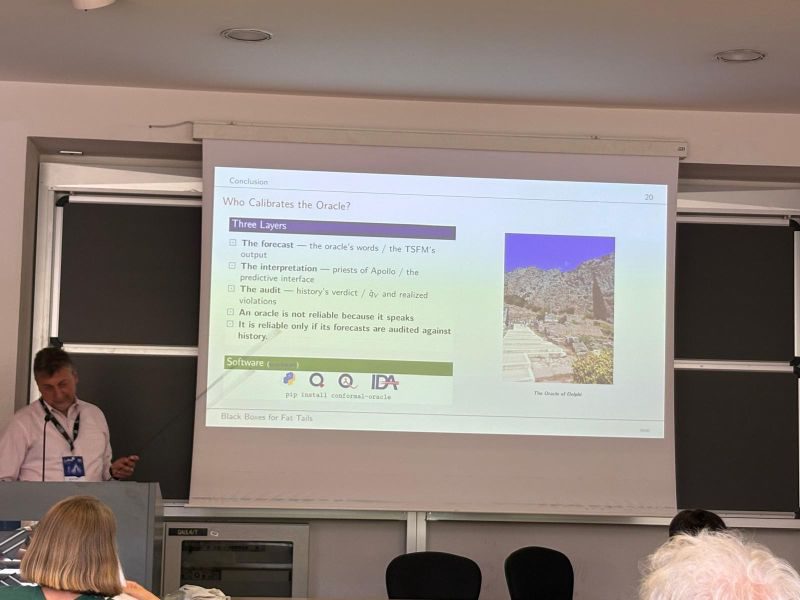
More recently, I study how large language models and time-series foundation models can be used to forecast risk, partly in joint work with my PhD students and the partners of the MSCA Doctoral Network on Digital Finance.
Latest
News
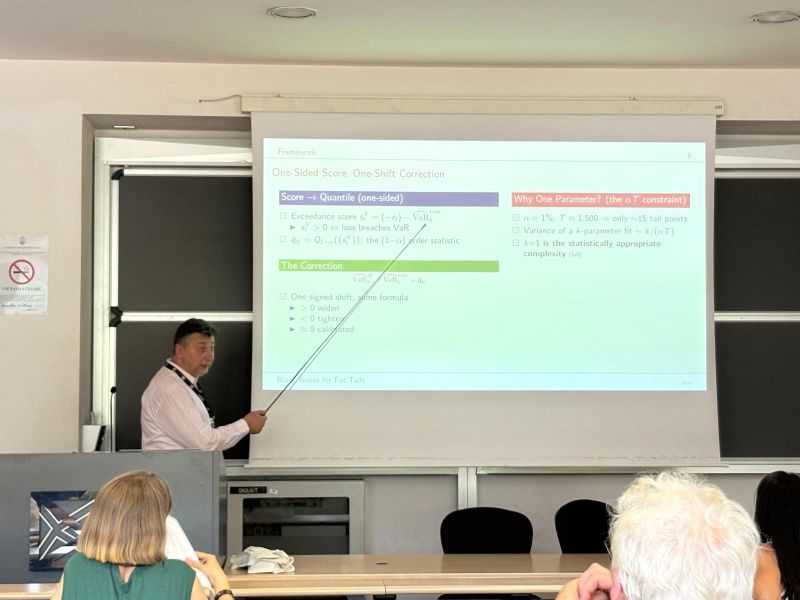
- New paper in Mathematics: “Finite-Sample Precision Limits for Expected Shortfall Forecast Comparisons”.Expected Shortfall precision depends on the effective tail sample size nα, not on n: at the 2.5% FRTB level, 250 days give about six tail observations. We turn this limit into practical diagnostics and find that roughly one in five pairwise ES rankings cannot be told apart, mostly where VaR is poorly calibrated.
What I work on
Research themes
Click a theme to see the matching publications.
Highlights
Selected papers
In the beginning was the Word: LLM-VaR and LLM-ES
Large language models forecast Value at Risk and Expected Shortfall, benchmarked against classical risk models with formal backtests.
Read the paper →Can Foundation Models Manage Risk? Zero-Shot VaR and ES Forecasting with Conformal Calibration in CEE Markets
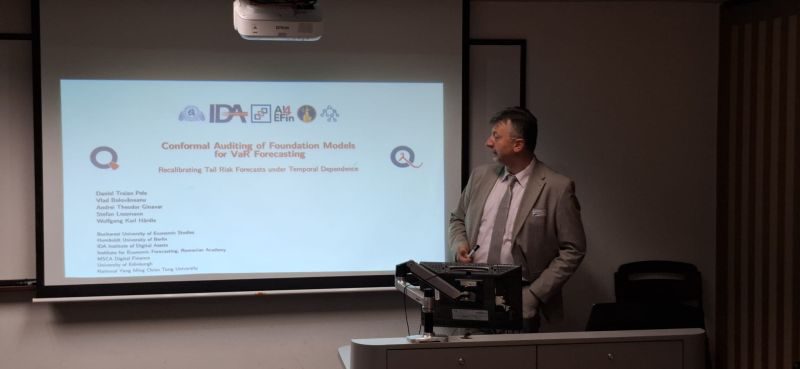
Zero-shot VaR and ES forecasts from time-series foundation models, recalibrated with conformal methods.
Read the paper →Quantlet: the code snippet knowledge platform
The Quantlet platform: every chart and table linked to runnable, citable code.
Read the paper →Are cryptos becoming alternative assets?
A statistical classification of cryptocurrencies against traditional asset classes.
Read the paper →Early warning systems for cryptocurrency markets: Predicting ‘zombie’ assets using machine learning
Machine-learning early warning for crypto-assets that turn into “zombies”.
Read the paper →BitMood: AI analysis of Bitcoin trends via Facebook emotions
Emotions in Facebook posts and their link to Bitcoin prices and trading volume.
Read the paper →Open courseware
Teaching
Open course websites with slides, seminars, notebooks, quizzes and runnable code for every chart.
Modelling Financial Markets
Econometrics of returns, volatility, tail risk, derivatives, machine learning, LLMs and foundation models for finance, on real data with reproducible code.
Statistics of Financial Markets
Returns and stylised facts, volatility, portfolio theory, VaR and Expected Shortfall, with lecture slides, seminars, Python notebooks and Quantlets.
Time Series Analysis
From exponential smoothing and ARIMA to unit roots, volatility models and forecasting evaluation, with code for every chart.
Advanced Time Series Analysis and Forecasting
Forecast evaluation, structural identification, state space and regime models, volatility and risk, machine learning, foundation models and causal inference, applied to real data in Python.
Blockchain Applications
Two parts: Crypto Economics (Prof. Ilan Alon), with business cases and a due-diligence project, and Blockchain Analytics: the statistics of crypto markets, from volatility and tail risk to stablecoin depegs, networks and machine-learning forecasts, with Colab notebooks.
Energy Markets Quantitative Analysis
Oil, gas and electricity prices: seasonality, spikes, ARIMA and GARCH, hedging and machine-learning forecasts.
Neural Networks and Deep Learning
Neural networks and deep learning with business applications.
Statistics of Financial Markets: code
SAS, R and Python code for the statistics of financial markets.
Also taught: Statistics, Econometrics, Advanced Time Series Modelling; supervision of bachelor, master and doctoral theses.